Construction Industry Monthly Snapshot by Barbour ABI
A monthly snapshot of the UK construction industry covering contract awards, planning approvals, and applications by sector, featuring expert commentary and detailed data visualisations.
Construction Industry Monthly Snapshot - October 2026⬇️
Source: Barbour ABI, September 2026 data
Contract Awards
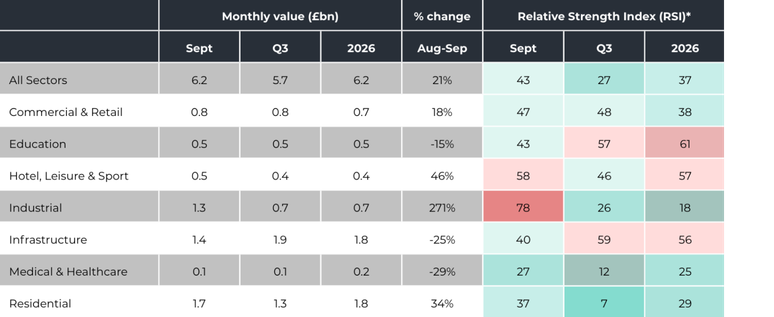
Contract awards rose 21% in September to £6.2bn, broadly in line with the 2026 average.
Growth was driven by a strong month for Industrial, with two of the largest awards also among September’s biggest approvals, suggesting some major schemes are moving quickly from approval to delivery.
Industrial more than tripled to £1.3bn, its strongest month since January 2025. The £450m Agratas Gigafactory fit out in the South West and the £250m Melbourn Science Park redevelopment in the East of England led the way, alongside a healthy mix of life science and logistics projects.
Residential grew 34% to £1.7bn with 44 projects above £10m, up from 29 in August. The largest was the £141m Stainton Vale Farm scheme of 587 houses in the North East, followed by the £100m Lea Bridge Gas Works redevelopment in London.
Infrastructure fell 25% to £1.4bn but still had the largest single award of the month, the £440m Point of Ayr CO2 Compression Station in Wales. Water and transport also featured, including the £120m South Kensington Tube Station redevelopment and the £110m River Mease Improvement in the East Midlands.
September presented a mixed but steady picture for UK construction. Awards recovered to around their 2026 average and approvals remained healthy at £9.8bn, while August applications came in at a modest £3.8bn with relatively few large projects entering the pipeline.
The Agratas Gigafactory and Point of Ayr CO2 Compression Station both appeared in September’s approvals and awards, showing that strategically significant industrial and energy schemes can move quickly once consented. Energy continues to underpin activity at every stage, from battery storage and solar applications to large-scale approvals such as Beacon Fen.
Residential was the most consistent performer, leading approvals at £4.3bn and growing in awards for a second month. A strong pipeline of large apartment and mixed-use schemes, particularly in the North West and London, suggests developers are maintaining confidence in longer-term housing demand despite ongoing affordability and financing pressures.
Growth does remain uneven. Medical & Healthcare was weak across all three stages, and a large share of total value continues to come from a small number of high-value projects, leaving monthly figures sensitive to the timing of individual schemes.
Overall, September suggests a market that is holding steady. Healthy approvals and a recovery in awards point to a solid flow of work into the final quarter but the issue remains in pushing these forward to activity on the ground, with plenty of economic headwinds still prevailing.
Contract Award Monthly Value by Sector (£bn)
No Data Found
Region Share of Award Value by Sector (%)
No Data Found
Monthly Highlights
Commercial & Retail increased 18% to £765m, driven by offices. Six of the top seven projects were office schemes, led by the £100m Sky office building at Kirkton Campus in Scotland and the £90m Project Heron refurbishment in London.
Hotel, Leisure & Sport rose 46% to £475m, with projects above £10m doubling from six to 13. The largest were the £60m Lancashire Court Estate in London and the £60m Farthing Stone Hotel redevelopment in the East Midlands.
Education dipped 15% to £475m, with the £65m Ysgol Llanhari Welsh medium school the largest award.
Medical & Healthcare fell 29% to £90m, with no project above £30m. The sector has now been subdued across applications, approvals and awards this month.
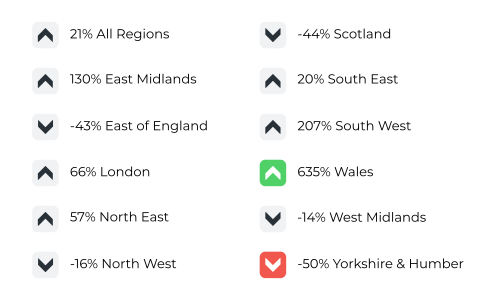
London was the top region at £1.3bn, helped by a strong run of office and residential awards. Wales saw the most dramatic rise, from £86m to £634m, its strongest month since January 2025 thanks to Point of Ayr. The South West tripled to £780m on the back of the Agratas Gigafactory, while Yorks & Humber halved to £267m.
Planning Approvals
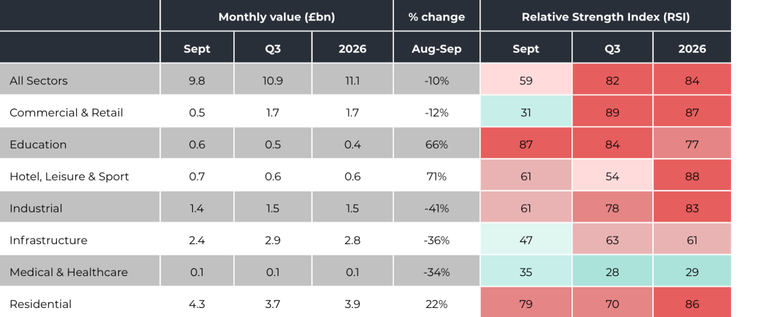
Planning approvals dipped 10% in September to £9.8bn, but the month was far broader based than August.
Projects above £10m rose from 147 to 181 and those above £100m from eight to twelve, with August’s total having been lifted by a handful of very large offshore wind and data centre schemes.
Residential led all sectors, rising 22% to £4.3bn with 85 projects above £10m. The largest were the £570m Crown Street Phase 3, a 1,746 apartment scheme in the North West, and The Lighthouse on Great Jackson Street at £234m.
Infrastructure fell 36% to £2.4bn, although August was boosted by £2.6bn from the two Caledonia offshore wind farms in Scotland. Energy remained the driver, led by the £580m Beacon Fen Energy Park in the East Midlands and the £440m Point of Ayr CO2 Compression Station in Wales.
Industrial dropped 41% to £1.35bn after August’s £1.5bn Graven Hill data centre campus. Over half of September’s value came from two projects: the £450m Agratas Gigafactory fit out in the South West and the £275m Metsa Tissue Paper Mill in Yorkshire.
Hotel, Leisure & Sport grew 71% to £655m, with projects above £10m more than doubling from seven to 16. The largest was the £100m King Alfred Leisure Centre redevelopment in the South East.
Education increased 66% to £610m with 15 projects above £10m, the largest being the £70m Fortis Academy teaching block in the West Midlands.
Commercial & Retail dipped 12% to £450m, with the £100m Sky office building at Kirkton Campus in Scotland the standout project.
Medical & Healthcare fell 34% to under £70m, with only two projects reaching £10m.
The North West was the top region, rising 89% to £1.4bn, with more than half coming from the two Manchester residential schemes. The South West saw the largest increase, up 232% to £1.2bn on the back of the Agratas Gigafactory, while the East Midlands tripled to £1.1bn thanks to Beacon Fen. Scotland fell 78% to £730m following its record offshore wind approvals in August.
Planning Approval Monthly Value by Sector (£bn)
No Data Found
Region Share of Approval Value by Sector (%)
No Data Found
Planning Applications*
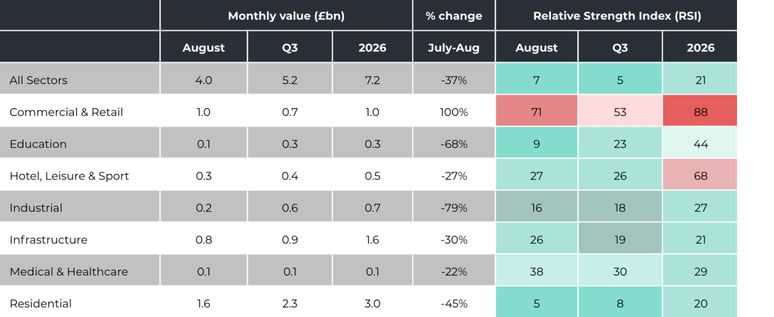
Planning applications totalled £3.8bn in August, with only 57 projects above £10m and six above £100m. Almost a third of the total value came from just four schemes.
Commercial & Retail was the strongest non-residential sector at £930m. However, 60% of this came from a single project, the £558m Cambois Hyperscale Data Centre Phase 2 in the North East, which was the largest application of the month by some distance.
Residential led all sectors at £1.6bn but had no project above £100m. The largest was 42 High Street, a £75m 729 apartment scheme in the West Midlands, with 25 projects above £10m spread across the regions.
Infrastructure reached £720m, driven almost entirely by energy and water. Major projects included the £150m Butlers Wood 500MW Battery Storage facility in the East of England and the £140m Ellesmere Port Wastewater Treatment Works upgrade in the North West.
Hotel, Leisure & Sport came in at £285m, with over a third of this from the £100m Regents House Hotel in Islington.
Industrial had a quiet month at £180m. Despite 287 applications, only three were above £10m.
Education totalled £130m, while Medical & Healthcare was the weakest sector at under £50m, with only two projects above £10m.
The North East was the top region at £720m on the back of the Cambois data centre and the £90m Hallfield Farm Battery Storage scheme. The West Midlands and Wales were the lowest at around £150m and £130m respectively.
Planning Application Monthly Value by Sector (£bn)
No Data Found
Region Share of Application Value by Sector (%)
No Data Found
*Planning Application data is subject to change post-publication due to the rigours within the verification process for newly submitted applications
Need a previous edition of the Snapshot?
Our team can help you access older reports on request. Just reach out and let us know what you need, we’ll be happy to assist.
Methodology for Construction Industry Monthly Snapshot
The Construction Industry Monthly Snapshot acts as a leading indicator of current and future activity in the construction industry. All values provided are at current prices, expressed in £bn unless stated otherwise and are non-seasonally adjusted.
The RSI is an index that measures current activity levels relative to the last 5 years. It is presented on a scale of 0-100, where:
● 0 is no activity, ● 100 is the maximum possible activity, and ● 50 is the average level of activity.
Sectors covered in the snapshot
The sectors that are included in the Construction Industry Monthly Snapshot are:
Our January edition of the snapshot features a review of the construction industry in 2025. This edition contains even more insight on the industry’s performance, including additional expert commentary, comprehensive data tables and concise visualisations.
Barbour ABI provides construction industry insights and intelligence. Head to our Construction Market Analysis Report pages to get even more free construction insights sent straight to your inbox every month.